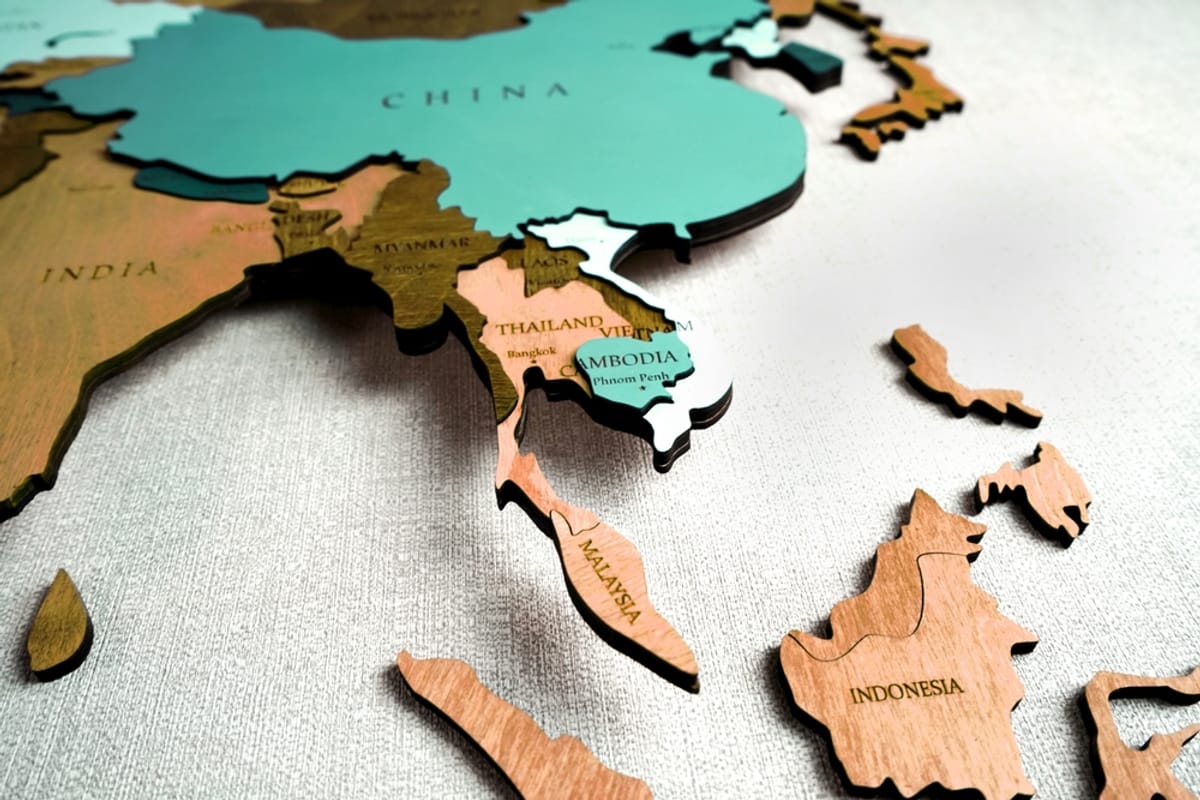
Asian countries are projected to see GDP growth of 3.1% to 4.1% in the 4th quarter of 2026.
We could see a slowdown or decline in Asian GDP and related construction growth due to the ongoing conflict in Iran in the 4th quarter of 2026.
China’s construction sector has seen a 25% to 30% drop in residential / housing work. However, there continue to be plenty of infrastructure projects being executed.
Ten to fifteen years ago, the majority of major U.S. and European industrial / manufacturing companies were directing their CAPEX capital investments into China. However, with all the recent political posturing, territorial disputes, and COVID-related shutdown issues, China has experienced a slowdown in foreign capital investment. We are seeing more U.S., Japanese, and Western European capital investment moving into India and, to a smaller extent, Vietnam. India is now viewed as a place to build new manufacturing / production facilities.
The Indian economy is one of the fastest growing among the world’s major countries. Assisted by government initiatives / investment programs, major Fortune 500 consumer-goods investments, and new technologies such as data centers, India’s construction industry is forecast to experience dynamic growth in the next 12 months. India is coming on strong and doing extremely well.
India overtook China as the world’s most populous country in 2025, with a population of 1.45 billion.
India’s construction and engineering sector offers numerous infrastructure projects, including highways, ports, and bridges. India plans to build at least five to seven new nuclear power plants in the next five years. These projects are focused on providing the industrial base that India needs to grow now and in the future.
India is currently experiencing a “golden” period and is one of the world’s fastest-growing economies. India’s construction sector is making significant headway. A visitor to India will see significant construction activity—roads, bridges, factories, and new buildings—in just about all of India’s 28 states and eight union territories.
India’s construction costs have increased by 7% to 11%, related to the Iran conflict, energy costs, petrol / diesel price increases, construction material costs, material shortages, labor costs, and freight costs. Aluminum, steel, paint, lumber, and electrical products are in short supply, and the waiting list to obtain some of these products can be four to eight weeks.
India and China are serious rivals. Both countries have stationed a significant number of troops in the disputed border region, which could turn out to be a “ticking time bomb” now and in the future.
Japan’s construction industry, for the seventh year, continues to experience slow or minimal growth in its civil / infrastructure, homebuilding, commercial, institutional, and industrial sectors, perhaps mirroring Japan’s steadily declining and aging population. The Japanese construction sector is estimated to be $600 billion to $750 billion in2026, or close to 8% of the country’s GDP.
Indonesia is the largest Southeast Asian nation, with a population of 280 million and located on hundreds of islands. Indonesia has sizable oil and gas, timber, and mineral resources. The Indonesian construction sector is valued between $200 billion and $230 billion per year; GDP growth is between 4.2% and 5.2%. There are numerous oil and gas, mining, and infrastructure projects being constructed. The future looks bright for the Indonesian construction sector.
South Korea has strengthened its standing as a leader in technology, microchips, shipbuilding, and FPSO construction. South Korea’s construction industry is performing reasonably well and has a reasonably healthy backlog that should last for the next 6 to12 months.
Other Asian countries, such as Malaysia, Singapore, Taiwan, Vietnam, and Thailand, appear to be set for construction-related growth in the 4th quarter of 2026, assuming the Iran conflict is diplomatically settled in the next 60 to 120 days.
The #1 question for the Asian construction sectors is how long the Iran conflict will last and whether it will cause inflation to spike in the next three to six months.