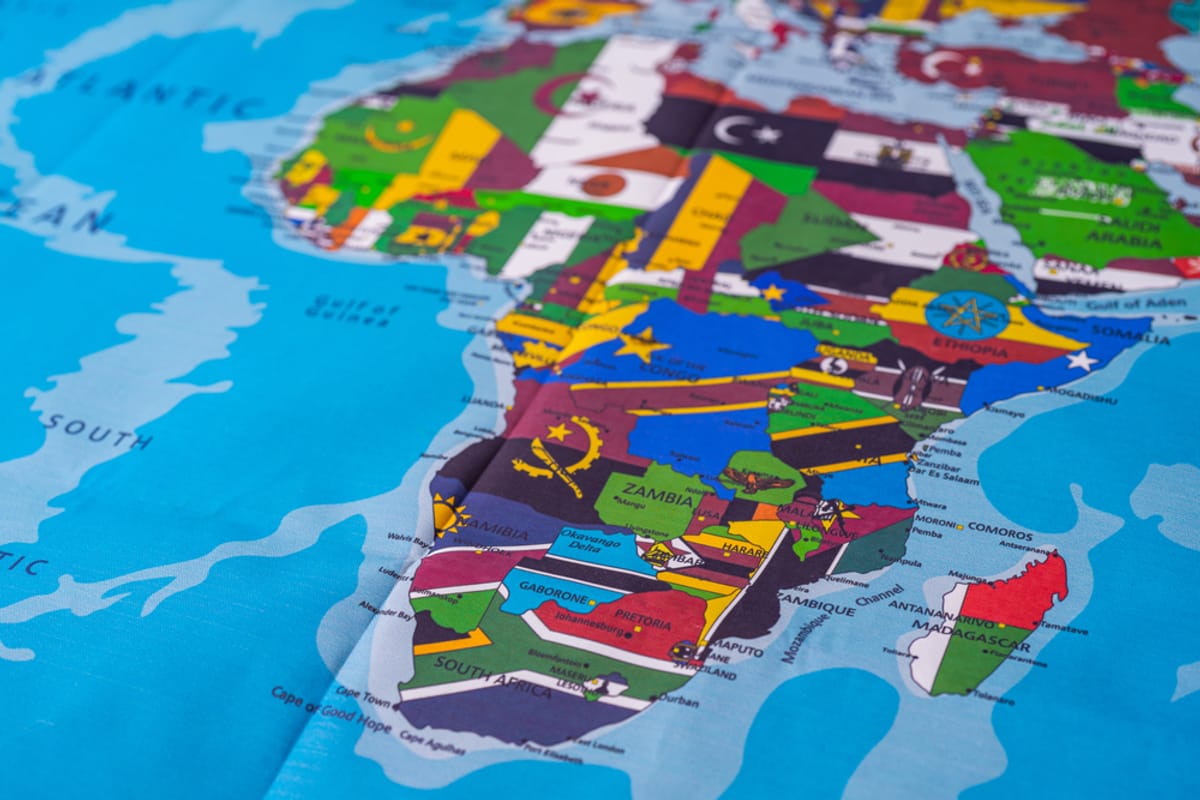
African nations are set to see minimal or, in some cases, negative GDP growth in the 4th quarter of 2026.
Africa’s construction sector stands at a critical pivot point. There are now two wars to contend with, one in Ukraine and one in the Middle East. Increased ocean freight could be very damaging to African nations.
Africa is forecast to be the next construction hotspot. In the next five to ten years, there will be a huge demand for new highways, railways, airports, housing, schools, hospitals, and other facilities. There will be a huge demand for A&E and construction services to meet this massive need. Africa’s construction market is forecast to be in the $80 billion to $90 billion range in 2026 and is forecast to grow to $125 billion to $150 billion by 2030.
The 54 countries that make up Africa should see construction-related growth for the most part, some better than others. The 4th quarter of 2026 should be a decent period for Africa’s construction industry.
Major African countries such as Nigeria, Egypt, Ethiopia, Kenya, Mozambique, and South Africa appear to have a good backlog of minerals / mining, oil and gas, LNG, and infrastructure projects in their immediate future.
One of the immediate challenges is that Africa’s population is forecast to grow to more than 2.5 billion in the next 25 years, from the current 1.2 billion. This growth will fuel the need for all kinds of construction projects across Africa’s 54 countries.
African countries continue to face high inflation, tariffs, shortages of skilled workers, and supply-chain material delays.
Infrastructure, oil and gas, minerals, and timber-related capital projects are the main drivers of the African construction sector. The African construction sector will continue to expand somewhat marginally in 2026, but look for a sustained improvement in 2027 / 2028.
The South African construction sector is forecast to grow by 2.1% to 2.6% in 2026. High unemployment, between 20% and 30%, and inflation continue to be significant challenges to the South African construction sector. The South African construction industry forecast for the 4th quarter of 2026 is rather subdued, with limited construction growth prospects on the horizon.
The Nigerian construction sector is estimated to be in the range of $140 billion to $185 billion in 2026, which makes it the #1 construction market in Africa. Nigeria’s new 650,000-barrel-a-day Dangote refinery recently came on stream with its first crude oil loading, which is a big plus for the country, which previously imported oil-related products.
Nigeria’s construction sector is forecast to grow by 3% to 5% in 2026. High inflation remains a continuing challenge. Nigeria is still challenged by the increasing cost of imported and domestic construction materials. The annual inflation rate in Nigeria is between 15% and 20%. For the Nigerian construction sector, this is a serious challenge.
Egypt will construct one of the largest wind farms in the Middle East, valued at more than $7.5 billion, by 2027. Also in the construction pipeline are plans to build a new nuclear plant, upgrades to Egypt’s petrochemical installations, and new railroad facilities. However, Egypt is experiencing high inflation, currently at 25%.
Mozambique’s construction sector is booming. LNG capital projects are moving forward, while roads, ports, and other civil-type projects are underway or in the planning pipeline.
Ethiopia’s construction industry is estimated to be in the $40 billion to $60 billion range as we move further into 2026. Ethiopia’s construction sector is developing, with a good number of infrastructure-related projects in the pipeline. The construction industry is estimated to grow by 5% to 6% in the next couple of years.
Some North African nations, including Algeria, Morocco, and Libya, are forecast to experience a slow but steady improvement in their economies and construction sectors compared with the three or four difficult previous years.
There is a massive need for new roads, bridges, airports / seaports, railways, and power/ energy-related projects across all of Africa in 2026 and beyond. It appears that there are a number of multibillion-dollar high-speed intercity and freight railroad bidding opportunities in Kenya, South Africa, and Ghana.
The #1 question for the African construction sector is whether the Iran conflict will be resolved in the next 60 to 120 days, or whether we will see a resumption of the U.S. bombing campaign. Will this continue, and will it drive up inflation in the next three to six months?